Weekend Update #295
Thank you for your continued support and engagement. Each week, we're sharing what companies we're researching and the what, the who and the how that we think makes the companies interesting and unique. This roundup is brought to you weekly by a group of interns, creative minds, artists and investors who believe that through best in class investing along with the democratization of financial education we can do great things together. Enjoy, Explore and Share.

Equity markets gained this week, with the S&P 500 reaching its first record close since August on Tuesday. Wednesday represented peak interest-rate pressure in Treasury markets, with the 10-year yield reaching 5.36% on Wednesday, the highest since April 2002, while the 30-year rose to 4.73%. A strong 10-year note action helped pause the selloff in Treasuries as indirect buyers took 80.3% of the sale against the 72.4% average, the strongest demand since 2016. Geopolitics remained in focus this week with Brent crude topping over $105 per barrel on Thursday. Axios reported that the U.S. military was prepping to launch major combat operations in Iran again, possibly before the November 3 midterm election. Markets got relief on Thursday when President Trump stated the U.S. will not resume strikes on Iran before midterms, reporting that the two countries are having productive discussions.
In economic data for the week, ISM Services PMI dipped to 54.9 in September while the prices paid index rose to 74.0, the highest since July 2022. The August trade deficit widened to $105.6 billion from $92.8 billion in the prior month and reached the widest since March 2025. The New York Fed’s Survey of Consumer Expectations for September showed year-ahead inflation expectations jumping to 3.90%, the highest since May 2023. Initial Jobless Claims for the week ended October 3 fell to 197,000, below the 200,000 consensus estimate, and the four-week moving average fell to the lowest since September 2022. The University of Michigan’s preliminary October Consumer Sentiment report showed a fall to 46.3, below the 47.6 median economist estimate and marking the 3rd straight month of sentiment declines. Year-ahead inflation expectations rose to 4.7% while long-run expectations rose to 3.5%, the highest readings since May. The Federal Reserve also released Meeting Minutes for the September FOMC meeting, which showed unanimous support among 19 officials for a rate hike. Most Fed officials are expecting another hike before year-end given strong economic growth and almost all members seeing inflation risks as tilted to the upside.
A report that OpenAI’s September annualized revenue was $50 billion shook AI-linked stocks this week, given the shortfall from reporting last month that annualized revenue was approaching $70 billion. Friday’s reporting revealed that OpenAI expects to reach the $70 billion figure by year-end. Samsung and TSMC both reported strong quarterly growth on continued AI demand but failed to exceed investor expectations, with shares of both companies falling after the reports. SpaceX agreed to purchase an 800 MHz spectrum portfolio from Grain Management to enable Starlink service in the U.S. mobile carrier market. Verizon, T-Mobile, and AT&T shares all fell on the news. Google signed a 20-year agreement with Constellation Energy for 3.6 GW of energy capacity to support the AI buildout, enabling $4.3 billion in new nuclear investment. Chipotle shares jumped on reports that Starbucks had considered a takeover of the company. Next week, investors will be focused on banks kicking off the Q3 2026 earnings season and an important CPI report for September due on Wednesday.
Friday’s Close (Weekly Performance)
S&P 500 7,811.54 (+1.15%)
Nasdaq 27,366.17 (+0.64%)
Dow Jones 51,654.95 (+0.93%)
Thank you Blue Room Senior Analyst JARED FENLEY
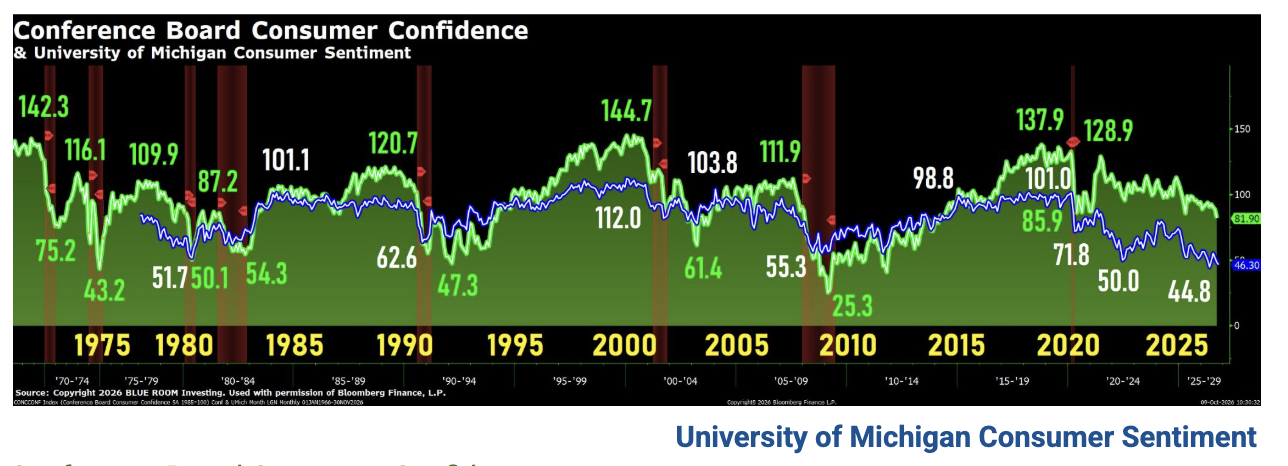
Consumer sentiment was little changed this month, inching down a scant 1.8 index points to 46.3 from September.
While year-ahead expectations for personal finances and business conditions crept up slightly, buying conditions for durables plummeted amid high prices and borrowing costs.
Increases in sentiment among Democrats and Republicans were offset by a decline among independents this month.
Overall, sentiment for lower-income consumers and those with smaller stock portfolios dropped steeply this month, groups that have fewer resources to weather increases in prices. Frustration over cost-of-living continues to mount, as consumers across the political spectrum believe that the trajectory of the economy has weakened since the beginning of the year.
Year-ahead inflation expectations ticked up from 4.6% last month to 4.7% this month. The current reading substantially exceeds the 3.4% seen in February before the Iran conflict began, along with all 2024 readings.
Long-run inflation expectations also stepped up from 3.4% in September to 3.5%, notably higher than their 2024 range of 2.8% to 3.2%. Inflation expectations over both time horizons increased for the second straight month to their highest readings since May.
Moderator
Patrick Trucchio — H.C. Wainwright
Question-and-Answer Session
Patrick Trucchio
H.C. Wainwright
Hello everyone, and thank you for joining H.C. Wainwright’s 28th Annual Global Investment Conference, held September 14–16, 2026. My name is Patrick Trucchio, and I’m a senior healthcare analyst at H.C. Wainwright. It’s my pleasure to introduce our next speakers from Precision BioSciences: CSO Cassie Gorsuch and CFO Naresh Tanna.
Precision is a clinical-stage gene editing company using its novel, proprietary ARCUS platform to develop in vivo gene editing therapies for diseases with high unmet need. The wholly owned pipeline includes PBGENE-HBV, which is in the Phase 1 ELIMINATE-B trial as a potential curative treatment for chronic hepatitis B, and PBGENE-DMD, which recently began dosing in the Phase 1/2 FUNCTION-DMD trial in Duchenne muscular dystrophy.
Welcome, and thank you for joining us again. For those less familiar with the story, can you give us some background on Precision’s platform, the technology, and the science that underpins the pipeline?
Cassie Gorsuch, Ph.D.
Chief Scientific Officer
Sure. Thank you very much, Patrick, for having us, and thank you all for joining us. It’s a pleasure to be here.
As Patrick said, Precision is a clinical-stage gene editing company. The common thread across all of our programs is our technology, which we call ARCUS nucleases. They are a unique platform of gene-editing nucleases that we designed wholly in-house. We own them, and we own all the IP around them. They have a few unique features that we think make them excellent gene editors for therapeutic applications.
The differentiators come down to three features: the cut, the size, and the simplicity of ARCUS nucleases. The cut allows us to take advantage of homology-directed repair for gene insertion. That type of edit is being used in an OTC deficiency program by our partner, iECURE, which relies on the unique overhang cut that ARCUS nucleases make to insert a healthy copy of the OTC gene.
Size is the second differentiator. ARCUS nucleases are very small, much smaller than the typical Cas9 protein in CRISPR-based systems, and that is an advantage when it comes to delivery.
Finally, simplicity: it’s a single-component editor. One protein binds DNA and cuts DNA, versus the multiple components needed in CRISPR-based systems: a guide RNA, a nuclease, and potentially a base editor on top of the Cas protein. We think the simplicity and elegance of this system provides a lot of flexibility in how we use the enzyme therapeutically.
Our approach is to take advantage of those unique features and apply them in therapeutic areas where the differentiators matter. Today, that is hepatitis B and Duchenne muscular dystrophy.


10% OF ALL BLUE ROOM REVENUES GO DIRECTLY TO FUND OUR NON PROFIT TOGETHERISM.
WE CAN ACCOMPLISH ANYTHING TOGETHER.
These materials do not purport to be all-inclusive or to contain all the information that a prospective investor may desire in considering an investment. These materials are intended merely for preliminary discussion only and may not be relied upon for making any investment decision. Any discussion or information contained in this presentation does not serve as a receipt of, or as a substitute for, personalized investment advice from Blueroom or your advisor.
This publication does not constitute an offer to sell or a solicitation to buy any securities in any fund, market sector, strategy or any other product. Investing is speculative and involves substantial risks (including, the risk of loss of the investor’s entire investment). Past performance is not indicative of future results, and there can be no assurance that the future performance of any specific investment, investment strategy, or product will be profitable.
For more information about us and our general disclosures contact us directly.